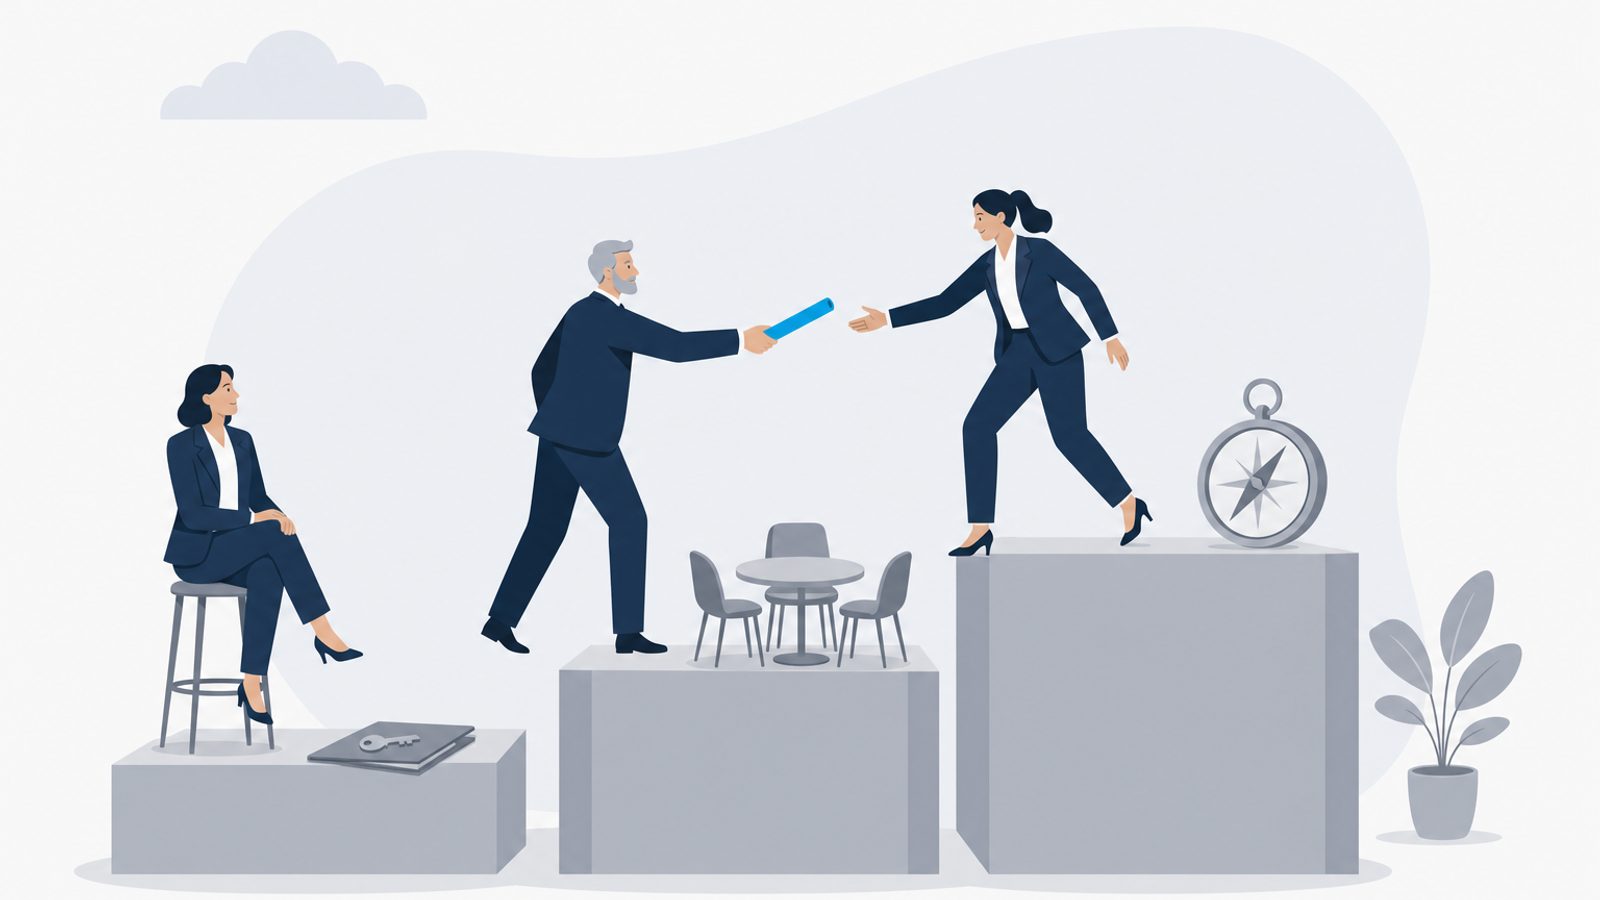
A family business succession plan usually answers one question: who comes next. It has to answer three. Ownership, governance, and management change hands on different clocks, and a plan that only names the next chief executive leaves the other two to settle themselves.
Most family owners treat their family business succession plan as the answer to a single question: who comes next? That question matters, but it covers only one of three handovers a family enterprise has to make. A plan that names the next chief executive and stops there leaves open who will own the company and who will govern it, and those open questions tend to unsettle the one the family thought it had answered.
International evidence points to the same gap. PwC's 12th Global Family Business Survey, published on October 13, 2025 and drawn from 1,325 family businesses in 62 countries (fieldwork April 1 to June 17, 2025), found that only 30% have a family constitution and only 9% have diverse boards. The report puts the consequence plainly: leadership transitions often lag because the next generation isn't fully prepared.
For an international reader, this matters in two places. Investors and co-owners in Mexican and Latin American family groups inherit the outcome of a succession they rarely see planned. And multinational partners working alongside family-controlled companies find that decision rights shift, sometimes abruptly, when one of the three handovers moves without the other two.
What does a family business succession plan actually cover?
A serious plan separates three handovers that families usually run as one.
Ownership. Who will hold the shares, in what proportions, under which shareholder agreements, and with what rules for entry, exit, or sale. This is estate-planning territory, worked with the family's legal and tax advisers, and its clock is set by the founders' lives and the structure of the family's wealth.
Governance. Who will chair the board, what role independent directors will play, and how the board relates to the shareholders' meeting and, where there is one, the family council. This is the stewardship handover: who will protect what the family entrusts to the enterprise beyond the interest of any one person or branch. Its clock is set by institutional maturity, not by anyone's age.
Management. Who will run the company and under what mandate. This is the visible handover and usually the only one families discuss. Its clock is set by the successor's real readiness to carry the scope of the role.
The three clocks run at different speeds. A founder can step out of management at sixty, chair the board for another decade, and keep a controlling stake for life. None of that is a mistake if it is decided and written down. The mistake is not knowing which handover is happening at any given moment.
Why do plans that only name a successor stall?
When the plan shrinks to naming the next chief executive, three familiar patterns show up.
The first is management without governance. The successor takes the title, but decisions still route through the founder, who no longer runs the company and has not stopped deciding. The board cannot sort this out because no one ever defined what management decides, what the board decides, and what the family decides.
The second is ownership mistaken for management. Siblings or cousins with equal stakes assume equal claims to run the business. Without written rules on how family members enter the operation and what a senior role requires, every appointment turns into a negotiation between branches.
The third is a board that cannot say no. A board made up of relatives and the founder's trusted advisers lacks the independence to read the successor candidly or to slow a premature appointment. PwC's survey singles out non-family perspectives through independent directors as a practice for objectivity, and it is where many Mexican family groups still have the most ground to cover.
How should a family read whether a successor is ready?
Readiness is not answered by the candidate's track record. Experience shows what someone has already done, not whether their judgment reaches the complexity of the role ahead. A daughter or son who has run a plant or a region well may have ample ability and still lack the capability to hold long-horizon, high-ambiguity decisions that ripple through the whole enterprise.
Three reads keep this straight. Ability is the practical skill the person already demonstrates. Capability is the judgment with which they navigate complexity: how they sense, frame, decide, and adapt. Capacity is the scale of work they can carry without breaking. Confusing them is the most expensive appointment error in a family succession.
Even large, well-advised families have not solved this. In the Deloitte Private survey of family enterprise leaders, published July 16, 2025 and covering 100 US family enterprises with revenues from US$100 million to over US$1 billion, only 49% felt well or very well prepared for leadership succession, and 31% named unclear selection criteria as an obstacle. Without criteria written before names come up, any read of a successor becomes an opinion about someone the family loves.
In what order should the plan be built?
Order matters more than speed. A sequence that holds in most family enterprises:
- The shareholder mandate. What the family wants the company to be in twenty years, what it will risk, and what it will not negotiate. Without that mandate, there is nothing to read any candidate against.
- Governance first. A board with independent directors, written rules on family entry into the operation, and a protocol that separates the decisions of the family, the board, and management.
- The criteria for the role. What the chief executive seat will demand in the years ahead, written before anyone thinks about candidates.
- The read of candidates. Family and non-family, read against the same criteria, with enough time for someone not ready today to develop.
- Ownership last. The transfer of shares aligned with everything above, worked through with the family's legal and tax advisers.
Reversing the order, starting with a name and leaving governance for later, produces most of the successions that stall.
What role should the board play in succession?
The board stewards continuity. Its job is not to pick the heir but to make sure the plan is built in the right order, that criteria exist before candidates, and that the read of the successor is candid. A well-composed board can tell a founder that the moment has not come yet, or that it already has. That is exactly the conversation a family-only board rarely sustains.
The succession at the top practice inside the Anker Bioss advisory model treats the three handovers as one architecture. Reading the chief executive seat, which we cover in how the board reads succession readiness, is one part of that architecture, not the whole plan.
If your family is starting the succession conversation, or has named a successor and decisions still are not moving, we can help separate the three handovers before the next step becomes urgent.
Frequently asked questions
When should a family business start its succession plan? Ideally ten to fifteen years before the founder expects to leave management. Governance and role criteria can be built at a measured pace. What cannot be rushed is a successor's development: the capability to hold long-horizon decisions forms through years of real exposure, not a last-minute program.
What is the difference between a family constitution and a succession plan? A family constitution, or family protocol, governs the relationship between the family and the business: who may work in it, how dividends are handled, how a shareholder exits. The succession plan uses those rules to sequence the three handovers. A plan without a constitution usually ends up negotiated person by person.
Does the successor have to be a family member? Not necessarily. Many strong family enterprises keep ownership and governance in the family while a professional chief executive runs the company for a period. What matters is that the decision is made against written criteria, not by elimination.
Who should coordinate a family business succession plan? The board of directors, supported by the family council where one exists. The founder takes part but cannot be the only designer of their own handover. An external facilitator helps when conversations between family branches need an independent read.